Relevance: TGPSC Group I Paper II: History, Culture and Geography
- Prelims: Nallamala Forest, Udimella, Padara mandal, Nagarkurnool, Tripuraraju, Mallidevaraju, Maninagapura, Udumisvara Deva, Saka Era.
- Mains: Inscriptional evidence, regional history, ruling lineage, temple donations, cultural heritage.
Why in News?
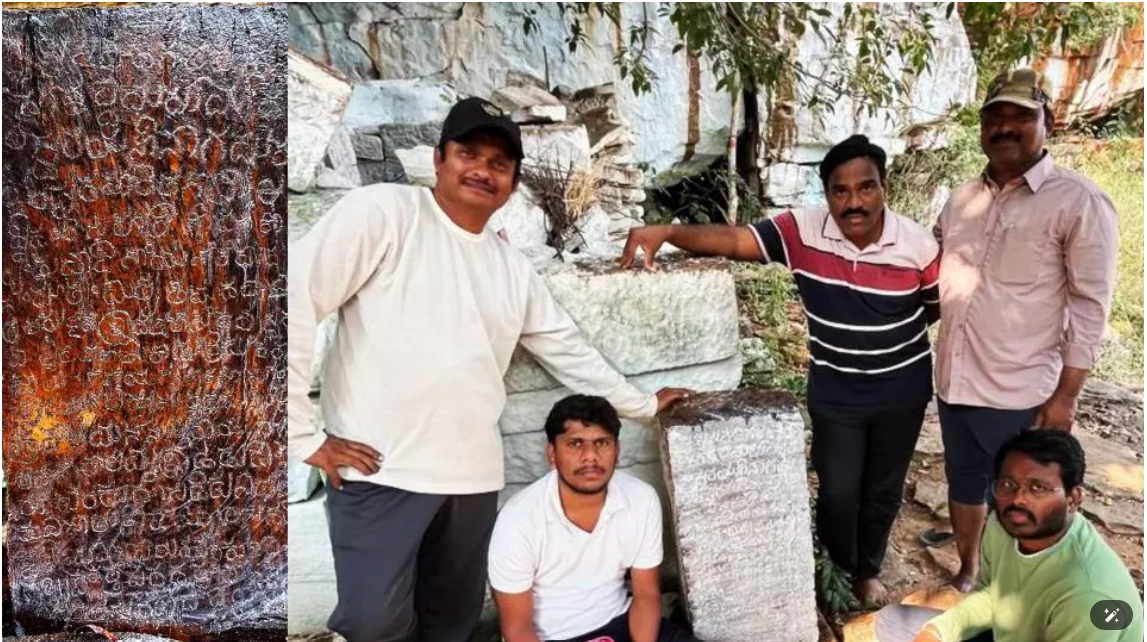
A historical inscription believed to belong to 1404 CE has been discovered near the ruins of a Shiva temple inside the Nallamala Forest.The site is located within the limits of Udimella in Padara mandal of Nagarkurnool district. The inscription belongs to the period of a ruler named Tripuraraju.
Location and Discovery
- The inscription was noticed by Karthik Pothuboyina of Vijayawada, a member of the Vedadri Nallagorla Trekking Team.
- The group explores temples, inscriptions and other historical sites in the Nallamala region.
Details Recorded in the Inscription
According to the reading of the inscription, Tripuraraju was the son of Mahamandalesvara Mallidevaraju.
Mallidevaraju is described as:
- belonging to the Hariti gotra;
- descending from the lineage of Madhavavarma;
- ruling Maninagapura; and
- possessing thousands of elephants and cavalry.
The inscription contains an eulogy praising Mallidevaraju’s rule and military strength.
Dating of the Inscription
The inscription mentions the Saka year 1990. However, researchers found this year to be incorrect.
Other chronological details recorded in it include:
- Tarana year
- Paushya Suddha Dasami
- Friday
- Uttarayana Sankramana
These details together correspond to December 14, 1404 CE. Therefore, researchers have dated the inscription to the beginning of the 15th century.
Religious Donations Recorded
The inscription records a donation made to Udumisvara Deva of Udumidla.
The donation was intended to provide:
- incense;
- lamps; and
- naivedya, or food offerings.
A separate donation to Visalakshi Jiyyelu Deva is also mentioned.
Conclusion
The inscription discovered at Udimella is an important addition to the historical record of the Nallamala region. It provides evidence about Tripuraraju, Mallidevaraju, their lineage and donations made for temple worship. Its similarity with the inscription found at Amanagallu may support further study of the political and religious history of medieval Telangana.
CARE MCQ
Q. Consider the following statements regarding the inscription recently discovered in the Nallamala Forest:
- It was found near the ruins of a Shiva temple in Nagarkurnool district.
- It identifies Tripuraraju as the son of Mahamandalesvara Mallidevaraju.
- It records a donation for incense, lamps and food offerings to Udumisvara Deva.
- Researchers confirmed the Saka year 1990 mentioned in the inscription as accurate.
Which of the statements given above are correct?
(a) 1 and 2 only
(b) 1, 2 and 3 only
(c) 2, 3 and 4 only
(d) 1, 2, 3 and 4
Answer: (b) 1, 2 and 3 only
Statement-wise Explanation
Statement 1 is correct: The inscription was found near a ruined Shiva temple at Udimella in Nagarkurnool district.
Statement 2 is correct: Tripuraraju is described as the son of Mahamandalesvara Mallidevaraju.
Statement 3 is correct: It records a donation for incense, lamps and naivedya to Udumisvara Deva.
Statement 4 is incorrect: Researchers found the recorded Saka year to be incorrect. The remaining chronological details correspond to December 14, 1404 CE.
FAQs
1. Where was the inscription discovered?
It was found near a ruined Shiva temple at Udimella in Padara mandal of Nagarkurnool district.
2. To which period does the inscription belong?
It has been dated to December 14, 1404 CE.
3. Who was Tripuraraju?
The inscription identifies him as the son of Mahamandalesvara Mallidevaraju.
4. What does the inscription say about Mallidevaraju?
It associates him with the Hariti gotra, Madhavavarma’s lineage and the rule of Maninagapura.
5. What religious donation is recorded?
It records donations for incense, lamps and food offerings to Udumisvara Deva and also mentions Visalakshi Jiyyelu Deva.
Relevance: UPSC GS Paper III: Science and technology, indigenisation, industrial policy and infrastructure
- Prelims: Semiconductor, silicon, transistor, integrated circuit, wafer, fabrication plant, semiconductor node, photolithography, ATMP, OSAT, Semicon 1.0, Semicon 2.0.
- Mains: Technological self-reliance, strategic autonomy, supply-chain resilience, advanced manufacturing, import dependence, domestic value addition, research and development, high-value employment.
Why in News?
The Union Cabinet approved Semicon 2.0 in July 2026 to deepen India’s semiconductor capabilities across the complete chip value chain.
India also organised SEMICON India 2026 at Yashobhoomi, New Delhi, from September 17 to 19. The event, themed “Silicon to Systems: Building the Ecosystem,” brought together industry leaders, policymakers, investors, academic institutions and start-ups.
What Is a Semiconductor?
A semiconductor is a material whose ability to conduct electricity can be controlled.
Materials can broadly be understood as:
- Conductors: Materials such as copper that allow electricity to flow easily.
- Insulators: Materials that strongly resist the flow of electricity.
- Semiconductors: Materials whose electrical behaviour can be controlled according to technological requirements.
Semiconductors can switch, amplify, sense or control electrical signals. This makes them the basic building blocks of modern electronic equipment.
From Sand to a Packaged Chip
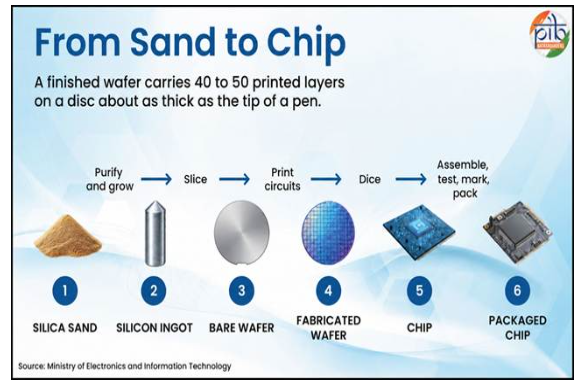
The transformation of ordinary silica sand into a semiconductor chip involves several precise stages.
Stage 1: Silicon Purification
- Silica is processed to obtain extremely pure silicon. Semiconductor manufacturing requires material with a high level of purity.
Stage 2: Ingot Formation
- The purified silicon is grown into a cylindrical silicon ingot.
Stage 3: Wafer Preparation
- The ingot is sliced into thin wafers. These wafers are polished to create smooth surfaces suitable for circuit fabrication.
Stage 4: Circuit Fabrication
The wafer undergoes hundreds of controlled operations inside a fabrication plant. Important processes include:
- Deposition: Addition of thin layers of material to the wafer
- Photolithography: Transfer of circuit patterns onto the wafer using light
- Etching: Removal of selected material to create circuit structures
- Ion implantation: Introduction of specific elements to modify electrical properties
These processes are repeated across several layers to create transistors, connections and other components.
A completed wafer may carry around 40–50 printed layers on a disc approximately as thick as the tip of a pen.
Stage 5: Dicing
- The fabricated wafer is cut into individual dies. Each functional die forms the central part of a semiconductor chip.
Stage 6: Packaging and Testing
- The die is assembled inside a protective package. Packaging allows the chip to communicate with other components of an electronic system.
- Testing determines whether the completed device meets the required performance and quality standards.
What Is a Semiconductor Node?
- A semiconductor node identifies a generation of chip-manufacturing technology.
- Earlier node labels such as 90 nanometres, 45 nanometres and 28 nanometres were closely related to specific physical measurements. Today, they mainly serve as names for different generations of manufacturing processes.
A smaller node can make it possible to place more transistors within the same chip area. This may provide:
- higher processing performance;
- lower power consumption;
- greater transistor density; and
- more features within the same chip size.
However, a smaller node does not automatically guarantee a better chip. Performance also depends on circuit design, materials, packaging and the purpose for which the chip is developed.

Advanced and Mature Nodes
- Advanced nodes support high-performance computing and leading-edge processors.
Mature nodes remain essential for:
- automobiles;
- industrial electronics;
- telecommunications;
- power systems; and
- consumer products.
India is developing capabilities ranging from established nodes towards more advanced technologies.
Applications of Semiconductors
Semiconductors are used across almost every modern sector.
Digital Technologies
- They support artificial intelligence, data centres, cloud computing, the Internet of Things and advanced communication systems.
Telecommunications
- Mobile phones, network equipment and 5G and 6G systems depend on semiconductor components.
Transport
- Automobiles, electric vehicles and autonomous vehicles require chips for control systems, sensors, batteries and safety functions.
Healthcare
- Medical equipment uses semiconductor devices for screening, diagnosis, monitoring and data processing.
Industry
- Robotics, automation, precision machinery and advanced manufacturing depend on specialised chips.
Strategic Sectors
- Defence systems, satellites, launch vehicles, unmanned aerial vehicles and naval and airborne systems require secure and reliable semiconductor supplies.
Global Semiconductor Value Chain
- The semiconductor value chain is highly specialised. No single country controls all its stages.
Different countries possess strengths in:
- chip design;
- fabrication;
- manufacturing equipment;
- specialised materials;
- memory chips;
- assembly; and
- packaging.
Taiwan, South Korea, Japan, China and the United States dominate global semiconductor manufacturing.
Taiwan accounts for:
- more than 60% of global chip production; and
- nearly 90% of advanced-chip production.
This geographical concentration creates supply risks during geopolitical tensions, industrial disruptions and other international crises.
The global semiconductor market grew at a compound annual growth rate of 6.5% between 2014 and 2024. It is projected to grow at approximately 8.5% over the next five to ten years.
Why Does India Need a Domestic Semiconductor Ecosystem?
Growing Demand
India’s semiconductor demand is projected to reach:
- $110 billion by FY2030; and
- more than $200 billion by FY2035.
The growth of electronics, telecommunications, electric mobility, artificial intelligence and digital services will further increase chip requirements.
Import Dependence
- India currently imports around 90–95% of the chips it consumes.
- Nearly $150 billion was spent on semiconductor-product imports between FY2017 and FY2025. Such imports grew at a compound annual rate of approximately 23%.
- If the trend continues, annual semiconductor imports could reach $240 billion by 2035.
Economic Security
- A domestic ecosystem can reduce the foreign-exchange burden associated with rising imports and retain a larger share of semiconductor-related economic activity within India.
National Security
- External dependence creates vulnerabilities in defence, telecommunications, space and other critical systems. Domestic capabilities can provide more reliable access to strategic chips.
Technological Competitiveness
- Chip capabilities are necessary for innovation in artificial intelligence, advanced communication, autonomous systems and high-performance computing.
Societal Development
- Domestic capacity can support wider access to modern electronic services, including affordable 5G and 6G connectivity.
India’s Existing Semiconductor Capabilities
India possesses a strong base in semiconductor design and engineering.
- The country employs nearly 20% of the global semiconductor chip-design workforce.
- It hosts approximately 7% of the world’s semiconductor-domain Global Capability Centres.
- More than one lakh engineers have received access to advanced chip-design tools.
- Academic institutions and start-ups are increasingly participating in chip development.
The Semiconductor Laboratory at Mohali has provided an institutional foundation for developing specialised chips required for strategic purposes.
Semiconductors in India’s Strategic Missions
The Semiconductor Laboratory develops flight-grade and radiation-resistant devices capable of functioning under extreme space conditions.
Its important contributions include:
- an Indian-made camera chip used in the Chandrayaan-3 lander;
- the Vikram processor used in satellite launch vehicles and rockets;
- radiation-hardened analogue-to-digital converter chips used in Aditya-L1; and
- flight-grade chips for satellites and launch vehicles.
These applications show India’s existing capacity to design semiconductor components for specialised national missions.
Semicon 1.0: Laying the Foundation
The Government approved Semicon 1.0 in December 2021 with an outlay of ₹76,000 crore.
The programme focused on creating the initial foundation for semiconductor and display manufacturing.
Major Components
- Scheme for setting up semiconductor fabs
- Scheme for setting up display fabs
- Support for compound semiconductors
- Support for silicon photonics and sensor facilities
- Incentives for ATMP and OSAT plants
- Design Linked Incentive Scheme
Major Achievements
Manufacturing Units
Twelve semiconductor manufacturing units were approved with a combined investment exceeding ₹1.64 lakh crore.
They include:
- one silicon fab;
- one silicon-carbide fab;
- one Gallium Nitride Micro-LED Display Fab; and
- nine ATMP/OSAT units.
The units are located in Gujarat, Assam, Uttar Pradesh, Odisha, Punjab and Andhra Pradesh. Five have commenced commercial production.
Chip Design
Twenty-four chip-design projects, valued at approximately ₹900 crore, were approved.
Advanced design tools were made available to over one lakh engineers from 500 organisations, including:
- 400 academic institutions; and
- 100 start-ups.
These organisations developed more than 300 chip designs.
Semicon 2.0: Building the Complete Ecosystem
Semicon 2.0 was approved with an outlay of ₹1,27,500 crore.
The programme seeks to expand India’s capabilities beyond fabs and packaging by developing all major parts of the chip value chain.
Six Pillars of Semicon 2.0
Design
- Development of strategic and commercial chips for Indian and international markets.
Machines and Materials
- Creation of capabilities in manufacturing equipment, specialised gases, chemicals and other essential materials.
Fabrication Facilities
- Establishment of additional silicon, compound-semiconductor and display facilities.
Packaging
- Expansion of conventional and advanced ATMP and OSAT capabilities.
Research
- Support for advanced nodes, emerging technologies and domestic semiconductor innovation.
Talent
Development of engineers, technicians, operators and researchers required by the semiconductor industry.
Semicon 1.0 and Semicon 2.0
| Semicon 1.0 | Semicon 2.0 |
| Established the initial ecosystem | Seeks to complete the value chain |
| Focused mainly on fabs and packaging | Adds materials, machines, research and talent |
| Expanded manufacturing and design | Deepens long-term technological capability |
| Created foundational capacity | Targets a globally competitive ecosystem |
Supporting Government Policies
National Policy on Electronics, 2019
It established the broad framework for Electronics System Design and Manufacturing, including chipsets and other electronic components.
SPECS, 2020
- The Scheme for Promotion of Manufacturing of Electronic Components and Semiconductors provides capital-expenditure-linked incentives for components, sub-assemblies and semiconductor manufacturing.
Modified Electronics Manufacturing Clusters Scheme, 2020
- EMC 2.0 supports common infrastructure, world-class facilities and plug-and-play manufacturing environments.
PLI for Large-Scale Electronics Manufacturing, 2020
- It promotes domestic manufacturing and investment in mobile phones and electronic components.
PLI 2.0 for IT Hardware, 2023
- It supports the domestic production of laptops, tablets, all-in-one computers and servers.
Electronics Components Manufacturing Scheme, 2025
- The scheme promotes component manufacturing and higher domestic value addition. Its outlay was enhanced to ₹40,000 crore in the 2026–27 Budget.
Mobile Phone Manufacturing Scheme, 2026
- It seeks to deepen the mobile-manufacturing supply chain, increase domestic value addition and support Indian mobile brands.
Research, Development and Innovation Scheme
- It supports eligible semiconductor research projects under Semicon 2.0.
Foreign Direct Investment
- India permits 100% FDI in electronics manufacturing, facilitating global investment, technological collaboration and value-chain integration.
International Semiconductor Partnerships
India has established semiconductor cooperation with:
- the United States;
- Japan;
- the European Union;
- Singapore; and
- the Netherlands.
During the German Chancellor’s visit in January 2026, India and Germany signed a Joint Declaration of Intent on a semiconductor ecosystem partnership.
- India also joined Pax Silica during the India AI Impact Summit in February 2026.
- These partnerships complement domestic capacity by supporting technology cooperation, investment and integration with global value chains.
Significance for India
Supply-Chain Resilience
Domestic capabilities can reduce India’s exposure to disruptions in geographically concentrated production networks.
Strategic Autonomy
Reliable access to domestically designed and manufactured chips can strengthen critical systems in space, defence, telecommunications and digital infrastructure.
Domestic Value Addition
Manufacturing more stages of the chip within India can retain investment, production and technical knowledge within the national economy.
High-Value Employment
Research, design, fabrication, equipment manufacturing and packaging can generate specialised employment for engineers, researchers, operators and technicians.
Global Competitiveness
India can combine its large chip-design workforce with expanding manufacturing capacity and trusted international partnerships.
Major Challenges
- Semiconductor manufacturing is among the world’s most complex industrial activities.
- India’s domestic fabrication capacity remains at an early stage.
- Advanced production is concentrated in a small number of countries.
- The complete ecosystem requires simultaneous progress in design, materials, machinery, fabs, packaging, research and talent.
- Manufacturing requires a high degree of precision and sustained technological development.
- The sector needs patience and consistent long-term policy support.
Conclusion
India’s semiconductor journey is progressing from design strength and strategic applications towards complete domestic manufacturing. Semicon 1.0 established the initial foundation, while Semicon 2.0 expands the mission to equipment, materials, research and talent. Long-term implementation can reduce import dependence, strengthen technological security and position India as a trusted participant in the global semiconductor ecosystem.
CARE MCQ
Q. Consider the following statements regarding India’s semiconductor ecosystem:
- Semiconductor nodes refer to generations of manufacturing technology.
- ATMP includes the assembly, testing, marking and packaging of fabricated chips.
- Semicon 2.0 is confined only to establishing silicon fabrication plants.
- India possesses nearly one-fifth of the global semiconductor chip-design workforce.
Which of the statements given above are correct?
(a) 1 and 2 only
(b) 1, 2 and 4 only
(c) 2, 3 and 4 only
(d) 1, 2, 3 and 4
Answer: (b) 1, 2 and 4 only
Statement-wise Explanation
Statement 1 is correct: A semiconductor node identifies a generation of chip-manufacturing technology.
Statement 2 is correct: ATMP represents the final stages of assembling, testing, marking and packaging chips.
Statement 3 is incorrect: Semicon 2.0 covers six areas—design, machines and materials, fabs, packaging, research and talent.
Statement 4 is correct: India employs nearly 20% of the global semiconductor chip-design workforce.
FAQs
1. Why is silicon widely used in semiconductor manufacturing?
Its electrical properties can be controlled, making it suitable for manufacturing transistors and integrated circuits.
2. What is photolithography?
It is the process of using light to transfer circuit patterns onto a semiconductor wafer.
3. What is the difference between a wafer and a chip?
A wafer is a thin silicon disc on which many circuits are fabricated, while a chip is an individual functional unit cut from that wafer.
4. What was the primary focus of Semicon 1.0?
It laid the foundation for semiconductor design, fabrication and packaging facilities.
5. What is the broader purpose of Semicon 2.0?
It seeks to develop a complete and globally competitive semiconductor ecosystem within India.
Relevance: UPSC GS Paper III: Indian economy, banking, financial inclusion and digital payments
- Prelims: Merchant Discount Rate, Unified Payments Interface, NPCI, P2P, P2M, P2PM, UPI AutoPay, payer bank, acquiring bank, TPAP, PSP.
- Mains: Digital public infrastructure, payment-system sustainability, financial inclusion, merchant formalisation, consumer protection, platform concentration, cashless economy.
Why in News?
The National Payments Corporation of India has announced a Merchant Discount Rate framework for specified UPI merchant payments. It will take effect from October 15, 2026.
The transition period will allow acquiring banks, payment aggregators, fintech applications and corporate accounting platforms to update their billing and software systems.
The announcement followed the government’s exemption of UPI payments up to ₹2,000 and RuPay debit-card transactions from bank charges.
What Is Merchant Discount Rate?
Merchant Discount Rate, or MDR, is a fee paid by a merchant to the entities that facilitate a digital transaction.
These entities include:
- banks;
- payment-service providers; and
- third-party UPI applications.
MDR is deducted from the merchant payment and distributed among different participants in the payment ecosystem. It is not designed as a direct charge on the customer making the payment.
Types of UPI Transactions
Person-to-Person
- A P2P transaction is a transfer between two individuals, such as payments to friends, family members or personal contacts.
Person-to-Merchant
- A P2M transaction occurs when an individual uses UPI to pay a registered business for goods or services.
Person-to-Person-Merchant
- P2PM is a special category covering micro-merchants, such as street vendors, who receive UPI payments through QR codes into personal bank accounts within the prescribed monthly limit.
MDR Rate Structure
| Transaction category | Applicable MDR |
| Regular merchant payment up to ₹2,000 | No MDR |
| Regular merchant payment above ₹2,000 | 0.4% |
| Regular merchant payment of ₹75,000 or more | Maximum ₹300 |
| Essential or thin-margin sector payment of ₹2,000 or more | Flat ₹5 |
| Specified capital-market payment | 0.02%, capped at ₹300 |
| P2P transfer | No MDR |
| Eligible P2PM payment | No MDR |
| UPI AutoPay or Mandate transaction | No MDR |
General Merchant Payments
- Mid-sized and large merchants receiving individual UPI payments above ₹2,000 will pay 0.4% of the transaction value.
- For a merchant payment of ₹75,000 or more, the levy cannot exceed ₹300.
Essential and Thin-Margin Sectors
A flat MDR of ₹5 will apply to eligible transactions of ₹2,000 or more in sectors such as:
- railways;
- telecommunications;
- insurance;
- fuel;
- electricity;
- water supply;
- piped gas;
- education; and
- agricultural inputs.
The fixed charge is intended to provide greater cost certainty to public services and businesses operating on narrow margins.
Capital-Market Transactions
- Payments involving mutual funds, securities, stockbrokers and dealers will attract an MDR of 0.02%, subject to a maximum of ₹300.
- The lower rate is intended to support retail participation in formal financial markets.
Which Transactions Are Exempt?
Individual Transfers
- All P2P payments will remain free irrespective of the value transferred.
- No transaction fee, platform charge or other levy can be imposed on individuals for sending or receiving money through UPI.
Automated Recurring Payments
Payments made through UPI Mandates or AutoPay will not attract MDR. These include:
- monthly utility bills;
- OTT subscriptions;
- recurring investments; and
- other standing instructions.
RuPay Debit Cards
- RuPay debit-card transactions have also been exempted from bank charges under the government’s announcement.
How Will Small Merchants Be Treated?
- Street vendors and other small merchants receiving up to ₹1 lakh per month through UPI QR codes into personal bank accounts will remain exempt under the P2PM category.
- They do not have to replace or re-register their existing QR codes.
- Banks and payment-service providers will use a transaction-velocity check to monitor the monthly inflow limit. A P2PM merchant receiving aggregate UPI credits exceeding ₹1 lakh per month for three consecutive months will be shifted to the regular P2M category.
- After this reclassification, individual merchant payments above ₹2,000 will attract the prescribed MDR.
Will Consumers Have to Pay?
- The government has maintained that customers will not directly bear MDR.
Banks have been advised to ensure that merchants do not pass the charge on to buyers. UPI applications are expressly prohibited from imposing:
- platform fees;
- hidden charges; or
- transaction fees on individual users.
- However, smaller or informal businesses may attempt to recover the charge through higher prices or encourage customers to pay in cash.
- NPCI has argued that merchants generally absorb nominal processing costs to gain higher business volumes. It has also stated that the UPI charge is significantly lower than card-processing charges and applies only above specified thresholds.
Why Has MDR Been Introduced?
Banks and other payment-system participants have so far borne the cost of operating UPI infrastructure.
The annual cost of maintaining the system is estimated at up to ₹20,000 crore. It covers:
- cloud storage;
- payment applications;
- transaction processing;
- security;
- settlement systems; and
- customer-support services.
The government’s position is that MDR revenue can support continued investment in digital-payment infrastructure.
Critics, however, argue that UPI provides wide public benefits and should continue as a no-cost digital public good. They fear that merchant charges could slow digital-payment adoption and encourage a return to cash.
Comparison with Card-Payment Charges
The basic UPI MDR is lower than conventional card-processing charges.
- UPI MDR: 0.4% on eligible merchant transactions
- Debit-card MDR: Capped at up to 0.90%
- Credit-card MDR: Generally between 1.5% and 2.5%
UPI also provides specific exemptions, reduced sectoral rates and a ceiling for high-value transactions.
How Widely Will MDR Apply?
- Different figures describe the MDR-eligible category because they use different denominators.
Share in Total UPI Volume
- P2P transfers constitute approximately 37% of all UPI transactions. Merchant payments up to ₹2,000 constitute another 60.5%.
- Together, these categories account for 97.5% of total UPI transaction volume and will remain free. Therefore, P2M payments above ₹2,000 represent only 2.5% of all UPI transactions by volume.
- The P2PM exemption makes the actual chargeable proportion still smaller.
Share in Merchant Payments
Within P2M transactions alone, payments above ₹2,000 accounted for:
- approximately 4% of merchant-payment volume in 2025–26; but
- nearly two-thirds of merchant-payment value.
Thus, high-value payments are few in number but account for a substantial share of the money transferred to merchants.
More than 24,000 crore UPI transactions, worth ₹314 lakh crore, were conducted during 2025–26.
| National Payments Corporation of India (NPCI)
1. Background
2. About NPCI
3. Legal Status
4. Purpose and Mission NPCI aims to:
5. Major Payment Systems
|
How Will MDR Be Distributed?
The reported distribution of MDR among payment-system participants is as follows:
| Participant | Share of MDR | Main responsibility |
| Customer’s or payer’s bank | 40% | Authorisation, account security and settlement |
| Merchant’s or payee bank | 30% | Merchant relationship, QR deployment and settlement |
| UPI application or TPAP | 20% | User-facing payment application |
| Payment Service Provider | 10% | Connecting the app and partner bank to the central UPI network |
Who Stands to Gain the Most?
Banking Segment
- Yes Bank is the payer bank in more than 50% of UPI transactions. It is followed by ICICI Bank, with approximately 18.3%.
- Yes Bank is also the receiving bank in about 55% of transactions, followed by Axis Bank, with around 19%.
- Its presence on both sides of the payment chain places Yes Bank among the largest potential beneficiaries.
UPI Application Segment
Among third-party application providers:
- PhonePe processes approximately 46% of UPI transactions by volume.
- Google Pay processes nearly 32%.
Their market shares give them the largest potential benefit from the portion allocated to UPI applications.
Potential MDR Revenue
- In August 2026, UPI transactions totalled approximately ₹29.8 lakh crore.
- P2M transactions above ₹2,000 were worth around ₹5.99 lakh crore, representing approximately 20% of the value of all UPI transactions.
Applying 0.4% to the entire amount produces a theoretical maximum of:
- approximately ₹2,400 crore per month; and
- around ₹28,000 crore annually.
Actual revenue will be lower because of sectoral flat rates, lower capital-market charges, transaction caps, AutoPay exclusions and small-merchant exemptions.
Fund for Small-Merchant Adoption
- The government will create a dedicated fund to encourage UPI use among small merchants.
- An amount equivalent to 5% of total MDR collections will be contributed to the fund. However, it has not yet been specified whether this contribution will come from banks, application providers, Payment Service Providers or a combination of participants.
Key Concerns
Indirect Burden on Consumers
- Merchants may attempt to recover MDR through higher prices or by asking customers to use cash.
Impact on Digital-Payment Momentum
- If merchants discourage UPI payments above ₹2,000, the framework could affect the shift from cash to digital payments.
Concentration of Revenue
- A substantial part of MDR income may flow to a small number of banks and UPI applications because they dominate transaction volumes.
P2PM Reclassification
- Small merchants crossing the ₹1 lakh monthly threshold for three consecutive months will enter the regular merchant category, increasing their payment-processing costs.
Lack of Clarity About the Fund
- The participant responsible for contributing the additional amount equivalent to 5% of MDR collections has not been identified.
Way Forward
- Enforce the prohibition on platform fees and hidden consumer charges.
- Monitor whether merchants recover MDR through higher retail prices.
- Communicate P2PM eligibility and reclassification rules clearly.
- Ensure that small merchants are not required to replace functioning QR codes.
- Publish transparent data on MDR collections and their distribution.
- Clarify how the small-merchant adoption fund will be financed and used.
- Periodically assess whether MDR affects digital-payment use or increases cash transactions.
- Balance payment-system sustainability with UPI’s role as accessible digital public infrastructure.
Conclusion
The MDR framework seeks to provide revenue for maintaining UPI infrastructure while protecting individual users, small payments and eligible micro-merchants. Although only a small proportion of transactions by volume will attract the levy, they represent a significant share of merchant-payment value. Effective consumer protection, transparent revenue sharing and careful monitoring of merchant behaviour will determine whether the framework strengthens the digital-payment ecosystem without weakening financial inclusion.
CARE MCQ
Q. Consider the following statements regarding the new UPI Merchant Discount Rate framework:
- Person-to-person transfers remain free irrespective of the amount transferred.
- Automated recurring payments made through UPI AutoPay are exempt from MDR.
- A P2PM merchant crossing ₹1 lakh in monthly UPI receipts for one month is immediately moved to the regular P2M category.
- Capital-market payments attract a lower MDR than general merchant transactions.
Which of the statements given above are correct?
(a) 1 and 2 only
(b) 1, 2 and 4 only
(c) 2, 3 and 4 only
(d) 1, 2, 3 and 4
Answer: (b) 1, 2 and 4 only
Statement-wise Explanation
Statement 1 is correct: Individual-to-individual payments remain free without an amount limit.
Statement 2 is correct: UPI Mandates and AutoPay transactions are excluded from MDR.
Statement 3 is incorrect: Reclassification occurs when aggregate monthly receipts exceed ₹1 lakh for three consecutive months.
Statement 4 is correct: Capital-market transactions attract 0.02%, while the general eligible P2M rate is 0.4%.
FAQs
1. When will the new MDR framework take effect?
It will become effective on October 15, 2026.
2. Does a customer have to pay MDR?
No. It is a charge within the merchant-payment ecosystem.
3. Are utility payments covered by the general 0.4% rate?
Eligible essential-service payments attract a flat charge of ₹5 instead of the general rate.
4. What happens when a small merchant repeatedly crosses the P2PM limit?
The merchant is moved to the regular P2M category after crossing the monthly limit for three consecutive months.
5. Why has MDR been introduced?
It is intended to help finance the operation and further development of UPI payment infrastructure.