Structure of Indian Banking System
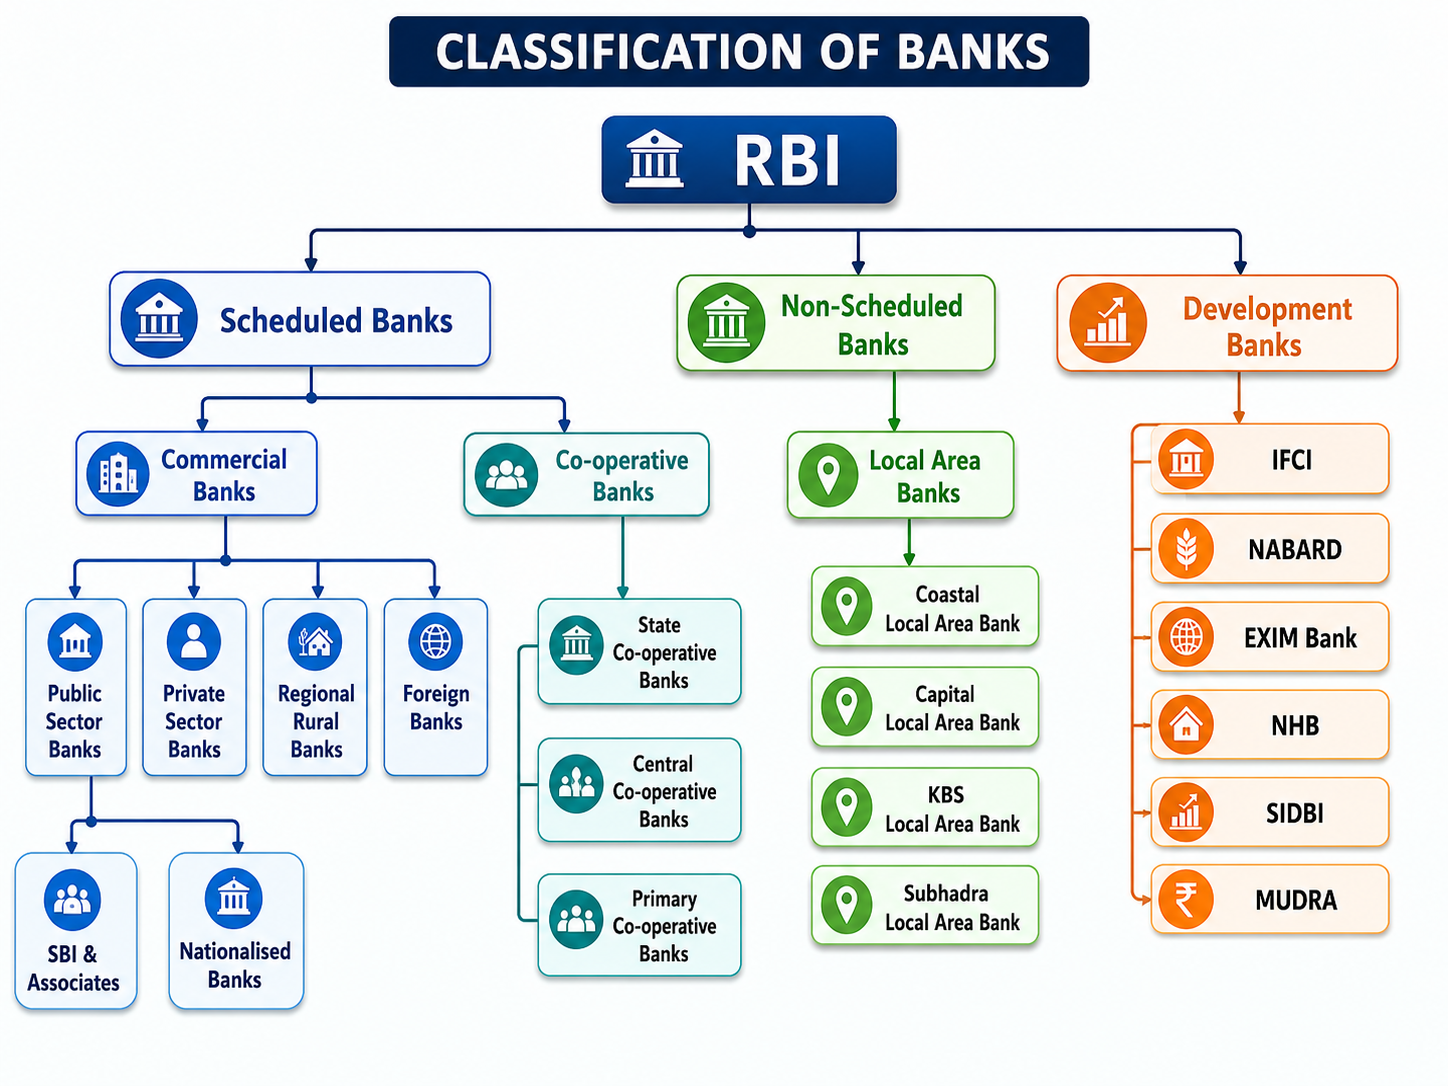
The banking system in India is broadly divided into Scheduled and Non-Scheduled Banks.
A. Scheduled Banks
- Included in the Second Schedule of the RBI Act, 1934.
- Maintain CRR (Cash Reserve Ratio) with RBI.
- Eligible for loans and clearing house facilities.
Types of Scheduled Banks:
-
Commercial Banks
- Public Sector Banks: Majority owned by Government of India. (Examples: SBI, PNB, Bank of Baroda)
- Private Sector Banks: Majority owned by private individuals/institutions. (Examples: HDFC, ICICI, Axis Bank)
- Foreign Banks: Incorporated outside India but operate in India. (Examples: Citibank, HSBC, Standard Chartered)
- Regional Rural Banks (RRBs): Established in 1975 under the RRB Act, sponsored by public sector banks to promote rural credit.
-
Co-operative Banks
- Work on principles of co-operation and mutual help.
- Categories:
- State Co-operative Banks (SCBs) – apex institutions at state level.
- District Central Co-operative Banks (DCCBs) – operate at district level.
- Primary Agricultural Credit Societies (PACS) – operate at village level.
- Provide credit mainly for agriculture and rural development.
-
Specialised Banks
- Small Finance Banks (SFBs): Provide credit to small businesses, farmers, unorganised sector (e.g., AU Small Finance Bank, Equitas).
- Payments Banks: Can accept deposits up to ₹2 lakh per customer but cannot lend (e.g., Paytm Payments Bank, India Post Payments Bank).
B. Non-Scheduled Banks
- Not included in the Second Schedule of RBI Act.
- Smaller in size and operations.
- Cannot borrow from RBI for routine operations.
- Example: Local Area Banks.
